Small Expenses That Eat Away At Your Savings
Retirement is supposed to be the time when you finally enjoy the money you've worked so hard to save, but that doesn't mean you should stop paying attention to where it goes. Whether you realize it or not, plenty of everyday expenses quietly drain your account once you're living on a fixed income. From forgotten subscriptions to generous gifts for the grandchildren, here are 20 things retirees spend too much money on.
1. Cable TV Packages
We know change is hard, but that’s no reason to stick with unfeasible things. Many retirees continue paying for expensive packages simply because they've had the same service for decades. However, a monthly bill of $150 can cost $1,800 annually, which is a decent chunk of change when you're trying to stretch your savings.
2. Gifts for the Grandchildren
There's nothing wrong with spoiling your grandchildren, but those little presents can become a substantial expense. Between birthdays, holidays, school fundraisers, and unexpected shopping trips, some grandparents dump hundreds of dollars more than they planned. To keep both parties happy, do yourself a favor and set a yearly gift budget that allows you to be generous without breaking the bank!
3. Grocery Store Convenience Foods
Precut vegetables, individually packaged snacks, and prepared meals make life easier, but it all does a number on your savings. Convenient options often cost more than buying ordinary ingredients and preparing meals at home, so there’s no need to splurge if you shouldn’t. You don't need to eliminate them entirely, but comparing prices can make a difference.
4. Maintaining a House That's Too Big
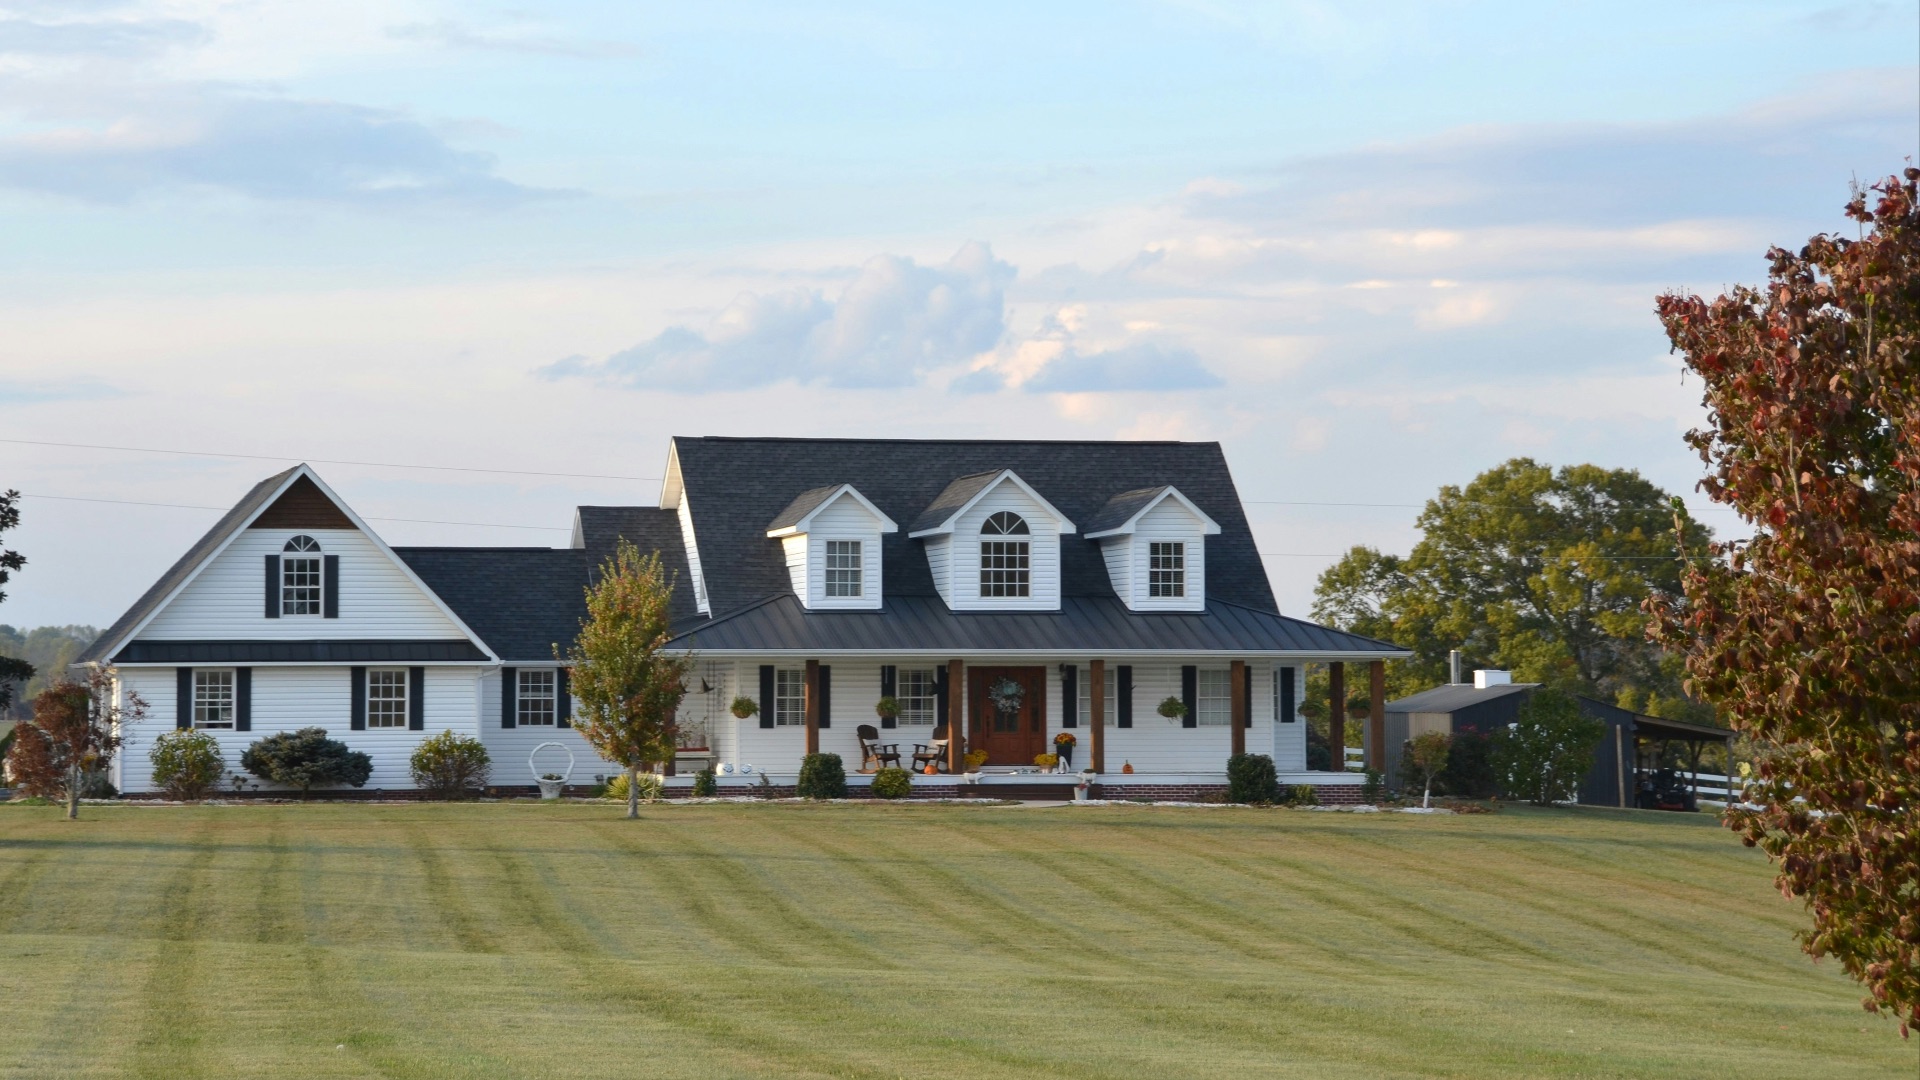
After the kids move out, some retirees stick around their humble abode—filled with unused bedrooms and bathrooms. As great as nostalgia is, heating, cooling, property taxes, insurance, and general upkeep make maintaining all that extra space far too expensive.
5. Medications at the Wrong Pharmacy
You might assume that every pharmacy charges the same for your medication, but prices can vary substantially depending on your insurance and the pharmacy you choose. Though it’s easier to fill prescriptions at familiar locations, less expensive options might be just around the corner. There’s no shame in stacking pharmacy prices against each other and asking about appropriate generic alternatives.
6. Restaurant Lunches
Having lunch with friends is a lovely way to stay social after retirement! However, spending $25 on lunch three times a week? Some quick math shows that adds up to approximately $3,900 over a year. Don’t feel pressured to head out every time; you can still enjoy time together at a potluck, picnic, or coffee date instead.
7. Coverage They Haven't Reviewed
It's easy to renew your home and auto insurance automatically—companies practically beg you to do so—but premiums and coverage needs can change. What does that mean for you? That you might be paying more than necessary for your current circumstances. Request quotes from competing insurers and review your policies annually to spot potential savings.
8. Hobbies They Barely Participate In
Retirement finally gives you time to explore interests you've been putting off, and while that’s normally a good thing, enthusiasm doesn't always translate into long-term commitment. Buying an expensive camera for photography or investing in golf equipment won’t do you any good if they collect dust in the basement. Before investing, consider renting equipment or taking an introductory class to determine whether you'll actually stick with something.
9. Heating and Cooling an Empty Home
When you're home more often, keeping the house at a comfortable temperature is pretty much a priority. Still, cooling an entire house can increase your utility bills unnecessarily. A programmable thermostat and properly adjusted heating or cooling zones, where your system supports them, may help lower expenses without making your home uncomfortable.
10. Unnecessary Bank Fees
Banks love to tack on little fees at the end of every month—or annually if you have credit cards. But retirees often overlook them; the charges are relatively small compared to their other expenses. Don’t write them off, though. A $15 monthly account fee costs $180 annually, and additional ATM or overdraft charges can increase that amount even more.
11. A Second Vehicle They Rarely Drive
Having two cars made sense when both of you were commuting, but retirement can change things. If one car spends most of its time in the driveway, you're just paying for insurance, registration, maintenance, and depreciation. If you don’t use it, look into selling it.
12. Too Much Food in Bulk
Warehouse stores sure do make those large quantities look appealing, especially when the price per item is lower. But it’s not much of a bargain if you buy enormous bags of fresh produce or meat you’ll never use in time. Retirees in smaller households may actually benefit more from buying manageable quantities.
13. Travel Upgrades They Don't Need
After decades of working, it's understandable that you might want to travel in style. After all, what’s the harm in finally enjoying those vacations you've always dreamed about? You still need to be practical, though! Upgrading every hotel room, booking premium excursions, and choosing expensive airport transfers can make an otherwise affordable trip considerably more expensive.
14. Products With High Management Fees
Some retirees pay investment management fees for years without really understanding how much those charges reduce their returns. For example, a 1% annual fee on a $500,000 portfolio amounts to $5,000 before accounting for changes in the portfolio's value. Reviewing your statements is always a good idea, but you should also ask a qualified professional to explain every expense.
15. Home Repairs
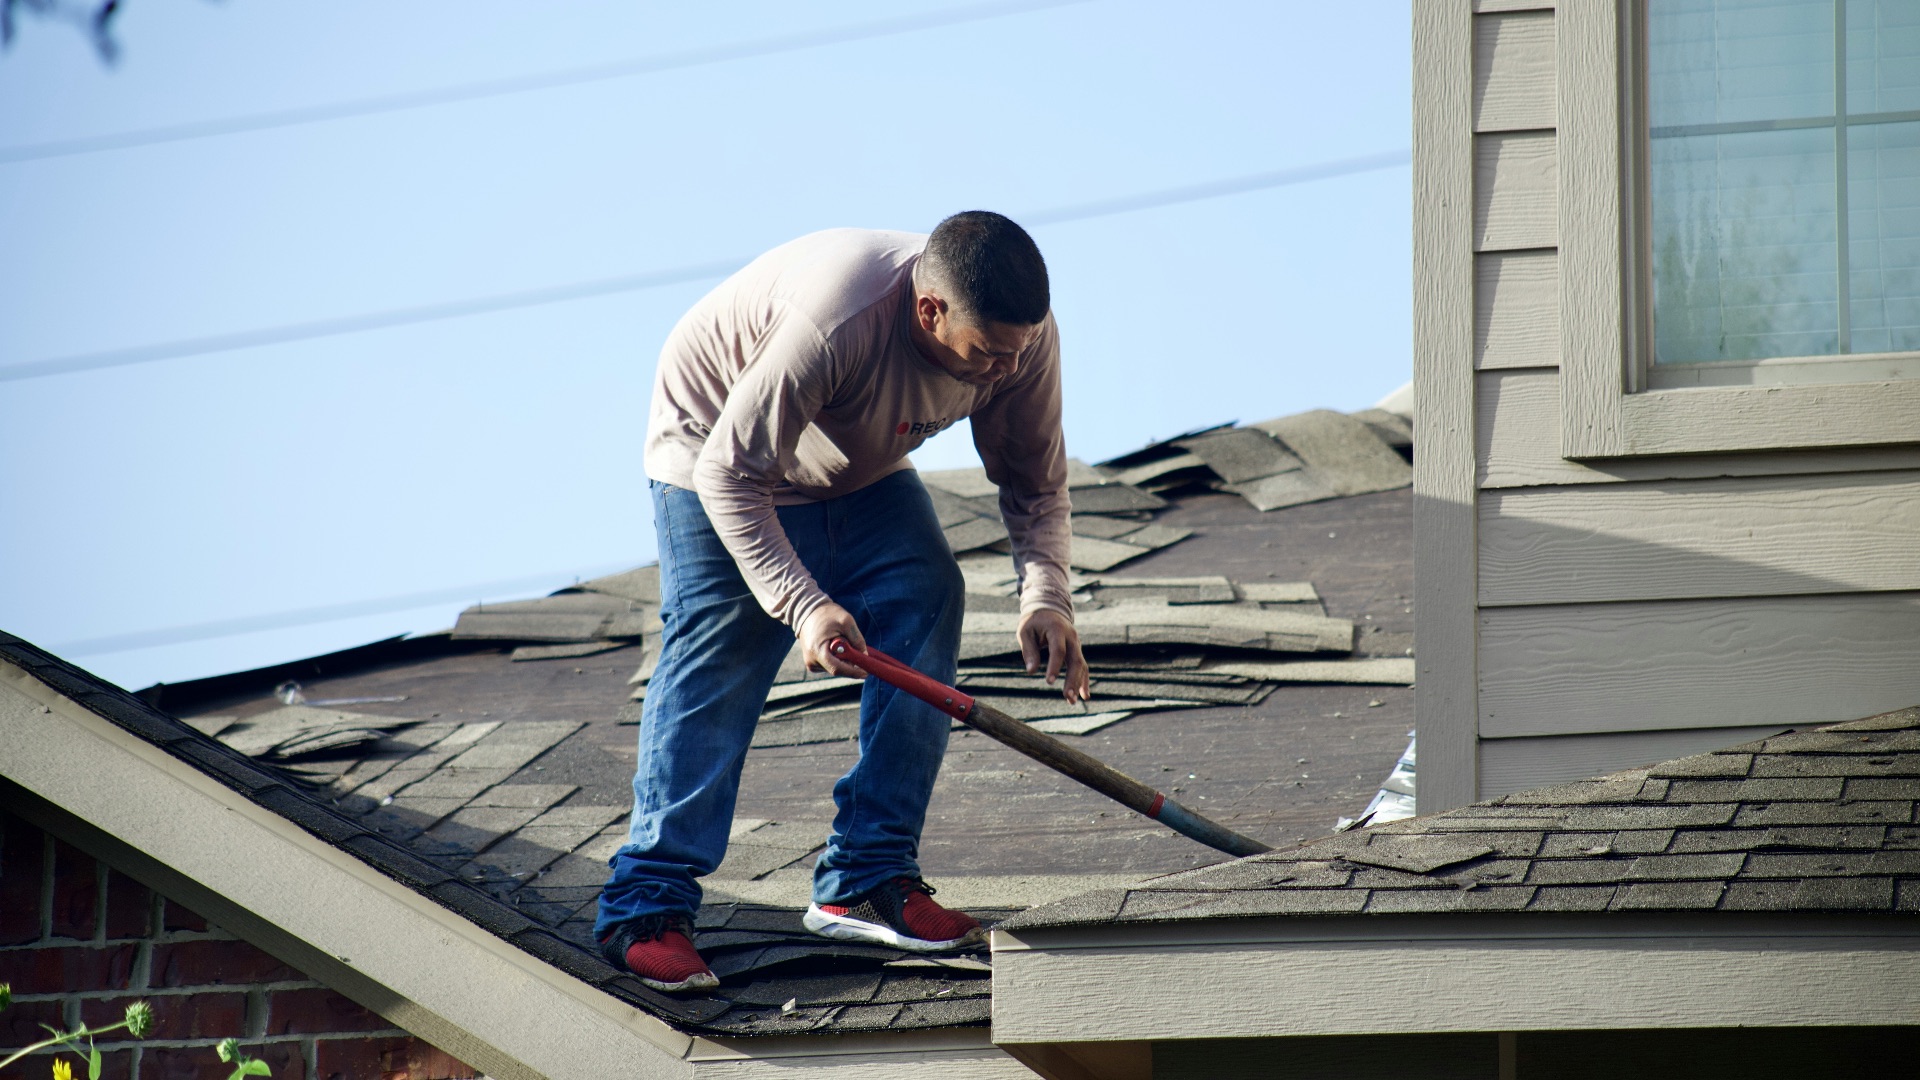
Putting off small maintenance jobs? That sounds like a good idea on paper, but ignoring a leaking faucet or damaged shingle can result in hair-raising repairs down the line. Taking care of minor problems as you spot them usually helps prevent the kind of unexpected bills that can disrupt a retirement budget.
16. Supporting Adult Children Financially
Parents obviously want to help their kids, even when they have families and careers of their own. But just how much are you helping them? Covering a grown child's phone bill, contributing toward rent, or repeatedly paying off credit card bills can quietly become a permanent responsibility. Not only that, it becomes a burden that isn’t your own!
17. Memberships They No Longer Use
That membership seemed like a great idea when you first retired—and it would still be great if you actually used it. There’s no shame in working out at home or pivoting to a new gym, but if you’re not using the machines, don’t pay for them! If you do stick with them, reviewing your memberships every few months ensures you're only paying for the stuff that still contributes to your life.
18. Replacing Things That Still Work
Having more free time can make shopping a tempting activity, even when there's nothing you really need. Next thing you know, you’re coming home with upgraded TVs, kitchen appliances, or furniture. Unless your current belongings actually fell apart, there's little reason to replace them.
 Nicolas J Leclercq on Unsplash
19. Services They Could Easily Cancel
Automatic deliveries, premium software plans, household service subscriptions—it never ends if you let them pile up! If you're still receiving monthly grooming products you rarely use, or paying for cloud storage that exceeds what you actually need, it’s time to sit down and take inventory of what you actually use.
20. Trying to Keep Up With Wealthier Friends
Retirement usually brings more chances to socialize, but not everyone in your circle has the same finances. Don’t try to keep up if the price tag keeps you up at night. Accepting every invitation to an expensive restaurant or costly weekend getaway can leave you spending beyond your comfort level just to participate.